L'80% dei costi è deciso prima che il prodotto esista. 80% of costs are decided before the product exists.
Un capitolo di 50 pagine di Davila e Wouters sul management accounting nella manifattura. Le 4-5 cose che mi sono rimaste in testa. A 50-page chapter by Davila and Wouters on management accounting in manufacturing. The 4–5 ideas that stuck with me.
Davila e Wouters mettono in fila la letteratura accademica su come le aziende manifatturiere gestiscono i costi in due fasi del ciclo di vita di un prodotto: durante lo sviluppo prodotto (New Product Development) e durante la produzione vera e propria (Modern Manufacturing Systems). Sono 50 pagine fitte di citazioni e referenze incrociate — qui condivido i passaggi che mi hanno fatto fermare a riflettere.
1. La rivelazione: 80%
Cooper & Slagmulder (1999), citati dagli autori, sostengono che l'80% dei costi di un prodotto viene deciso durante la fase di sviluppo, non in quella di produzione. Quando il prodotto è in linea di assemblaggio, i giochi sono già fatti: ogni componente, ogni tolleranza, ogni materiale è stato scelto in fase di design. Le aziende che vogliono ridurre i costi devono farlo prima che il prodotto esista fisicamente.
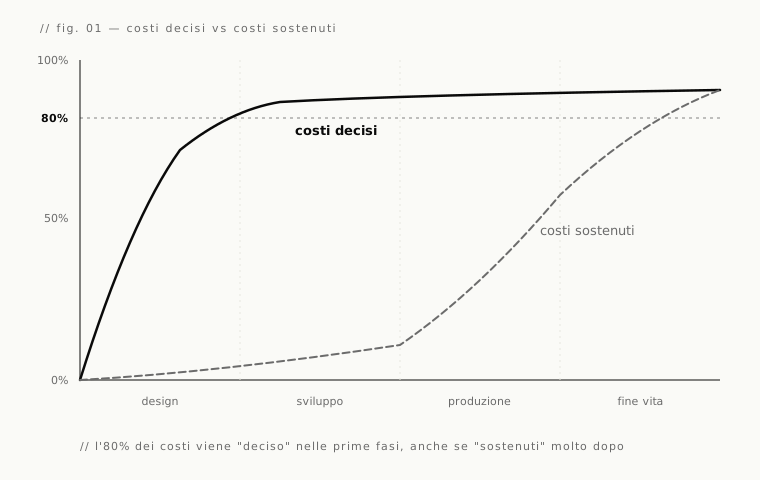
È un cambio di prospettiva forte: uno studio di fattibilità non è "calcolare i costi previsti", è "decidere quali costi avere". Sono due attività diverse, con responsabilità diverse.
2. Target costing — e quando non basta
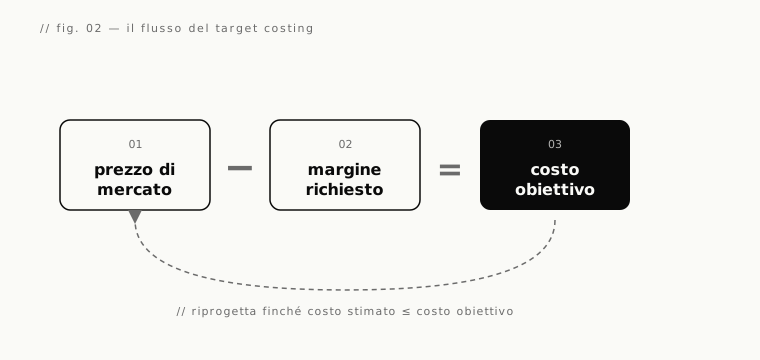
Il target costing è la tecnica più studiata per gestire i costi durante il design. Funziona così: si parte dal prezzo di mercato a cui il prodotto dovrà essere venduto, si sottrae il margine richiesto, e si arriva a un costo obiettivo. Il team di sviluppo deve stare dentro quel budget, riprogettando se necessario. È una disciplina rigorosa, e funziona bene quando il prezzo è la dimensione competitiva principale (commodity, automobili economiche, elettronica di consumo).
Ma se la concorrenza si gioca su tecnologia, time-to-market o customizzazione, il target costing perde efficacia. Davila & Wouters elencano alternative:
- Specialisti dei costi integrati nei team di sviluppo (Hertenstein & Platt, 2000).
- Team paralleli che ottimizzano i sotto-sistemi dopo che il design principale è fatto.
- Modularità: progettare i sotto-sistemi non critici come "scatole nere" riusabili (Baldwin & Clark, 2000).
- Design for X (Manufacturing, Assembly, Recycling, Serviceability): euristiche pensate per ridurre i costi a valle.
- Parts e process commonality: ridurre la complessità condividendo componenti e processi tra prodotti diversi.
3. Misurare l'R&D resta un problema irrisolto
La cosa che mi ha colpito di più: anche nel 2007 — e suppongo ancora oggi — non esiste un consenso su come misurare la performance dell'R&D. Hertenstein & Platt (2000) riportano che i manager danno 4.9 su 10 alla qualità attuale dei loro sistemi di misurazione, contro un desiderato di 7.2. C'è una distanza ammessa apertamente tra cosa si vorrebbe misurare e cosa si riesce.
Vengono usate metriche finanziarie (IRR, ROI, percentuale di fatturato da nuovi prodotti, R&D effectiveness index), non-finanziarie (time-to-market, qualità del processo, soddisfazione del cliente sul prototipo), a vari livelli di aggregazione: singolo progetto, portafoglio di progetti, funzione R&D, intera organizzazione. Le real options sono state proposte per valutare il valore di investimenti ad alto rischio. Ma il punto resta: nessuna metrica funziona davvero da sola.
R&D departments doing external work use more objective measures. — Drongelen et al. (1999), citato nel capitolo
4. Modern manufacturing: il problema degli investimenti intangibili
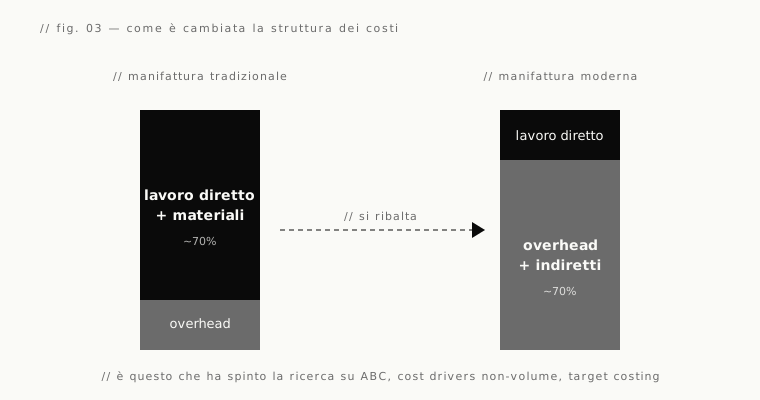
Quando un'azienda investe in tecnologie produttive moderne — robotica, MRP, sistemi flessibili, computer-integrated manufacturing — i benefici sono spesso intangibili: maggiore qualità, tempi di consegna più rapidi, capacità di personalizzare, maggiore flessibilità di volume. Tradurre questi benefici in numeri finanziari per giustificare l'investimento è difficile, e il rischio è che progetti strategicamente sensati vengano bocciati dall'analisi finanziaria tradizionale.
L'evidenza empirica raccolta nel capitolo dice che la maggioranza delle aziende prova comunque a quantificare i benefici intangibili dentro l'analisi finanziaria — anche con approssimazioni rozze — piuttosto che escluderli del tutto. Abdel-Kader & Dugdale (1998) mostrano che sette benefici tipici degli MMS vengono comunque tradotti in numeri: riduzione del costo del lavoro, dei materiali, delle scorte, degli scarti, aumento del volume di vendita, risparmi sui setup, aumento della capacità produttiva.
Payback period e IRR restano i criteri più usati nella pratica, anche se la teoria finanziaria preferirebbe il NPV. E c'è un'evidenza interessante: le aziende non sempre alzano il tasso di sconto per riflettere il maggior rischio degli MMS — il che è in contrasto con quello che la corporate finance suggerirebbe.
5. Cosa porto via
Tre cose:
- Il design è dove i costi si fanno, non la produzione. Cambia dove metti l'attenzione, e cambia chi è responsabile per cosa.
- La misurazione è un problema aperto, non una scienza esatta. Sentirsi insicuri davanti alle metriche è giustificato — anche i ricercatori lo sono, e lo dichiarano apertamente.
- Le aziende inventano workaround. Sul campo, se la teoria dice "X" ma la realtà è complessa, le aziende combinano tecniche (target costing + ABC + value engineering + DFX). Niente è "puro" nella pratica, ed è proprio dove sta il lavoro interessante.
Il fatto che molta della ricerca riportata abbia 15+ anni e che le domande di fondo restino aperte mi conforta: c'è ancora spazio per chi vuole entrare in questi temi senza dover essere l'esperto definitivo prima ancora di iniziare.
Davila and Wouters lay out the academic literature on how manufacturing firms manage costs across two phases of a product's lifecycle: during product development (New Product Development) and during actual production (Modern Manufacturing Systems). The chapter runs fifty pages, dense with citations and cross-references — here I share the passages that made me pause.
1. The 80% reveal
Cooper & Slagmulder (1999), cited by the authors, argue that 80% of a product's costs are decided during the development phase, not during production. By the time a product hits the assembly line, the game is over: every component, every tolerance, every material has been chosen at the design stage. Companies that want to reduce costs must do so before the product physically exists.
It's a sharp shift in perspective: a feasibility study isn't "calculating expected costs", it's "deciding which costs to have". Two different activities, with different responsibilities.
2. Target costing — and when it falls short
Target costing is the most studied technique for managing costs during design. It works like this: start from the market price the product will sell at, subtract the required margin, and arrive at a target cost. The development team has to stay within that budget, redesigning if needed. It's a rigorous discipline, and it works well when price is the main competitive dimension (commodities, economy cars, consumer electronics).
But if competition is played on technology, time-to-market or customization, target costing loses effectiveness. Davila & Wouters list alternatives:
- Cost specialists embedded in development teams (Hertenstein & Platt, 2000).
- Parallel teams that optimize sub-systems after the main design is done.
- Modularity: designing non-critical sub-systems as reusable "black boxes" (Baldwin & Clark, 2000).
- Design for X (Manufacturing, Assembly, Recycling, Serviceability): heuristics meant to reduce downstream costs.
- Parts and process commonality: reducing complexity by sharing components and processes across products.
3. Measuring R&D is still an unsolved problem
What hit me most: even in 2007 — and I suspect today too — there's no consensus on how to measure R&D performance. Hertenstein & Platt (2000) report that managers give 4.9 out of 10 to the current quality of their measurement systems, against a desired 7.2. There's an openly acknowledged gap between what people want to measure and what they manage to.
Financial metrics get used (IRR, ROI, percentage of revenue from new products, R&D effectiveness index), non-financial ones too (time-to-market, process quality, customer reaction to prototypes), at various levels of aggregation: single project, project portfolio, R&D function, the whole organization. Real options have been proposed to value high-risk investments. But the point stands: no single metric really works on its own.
R&D departments doing external work use more objective measures. — Drongelen et al. (1999), cited in the chapter
4. Modern manufacturing: the problem of intangible benefits
When a firm invests in modern production technologies — robotics, MRP, flexible systems, computer-integrated manufacturing — the benefits are often intangible: higher quality, faster delivery times, customization capacity, volume flexibility. Translating these into financial numbers to justify the investment is hard, and the risk is that strategically sound projects get rejected by traditional financial analysis.
Empirical evidence collected in the chapter shows that most firms try to quantify intangible benefits inside the financial analysis anyway — even with rough approximations — rather than excluding them entirely. Abdel-Kader & Dugdale (1998) show that seven typical MMS benefits do get turned into numbers: reduced labor costs, material costs, inventory, scrap, increased sales volume, setup savings, increased production capacity.
Payback period and IRR remain the most-used criteria in practice, even if financial theory would prefer NPV. And there's an interesting piece of evidence: firms don't always raise the discount rate to reflect the higher risk of MMS — which contradicts what corporate finance would suggest.
5. What I take away
Three things:
- Design is where costs are made, not production. It changes where you put your attention, and it changes who is responsible for what.
- Measurement is an open problem, not an exact science. Feeling unsure when looking at metrics is justified — even researchers are, and they say so openly.
- Companies invent workarounds. In the field, when theory says "X" but reality is complex, companies combine techniques (target costing + ABC + value engineering + DFX). Nothing is "pure" in practice, and that's exactly where the interesting work is.
The fact that much of the research cited is 15+ years old and the fundamental questions remain open is actually reassuring: there's still room for those who want to enter these topics without having to be the definitive expert before they even start.